TRENDING
Wednesday, 28 October 2026
----------------------
17 Jumada Al-Awwal 1448 AH
Global equity markets surged as investors poured money into AI, lifting tech giants but masking deeper costs. The rally reveals who profits, who bears the burden, and what signals lie beneath the headlines.
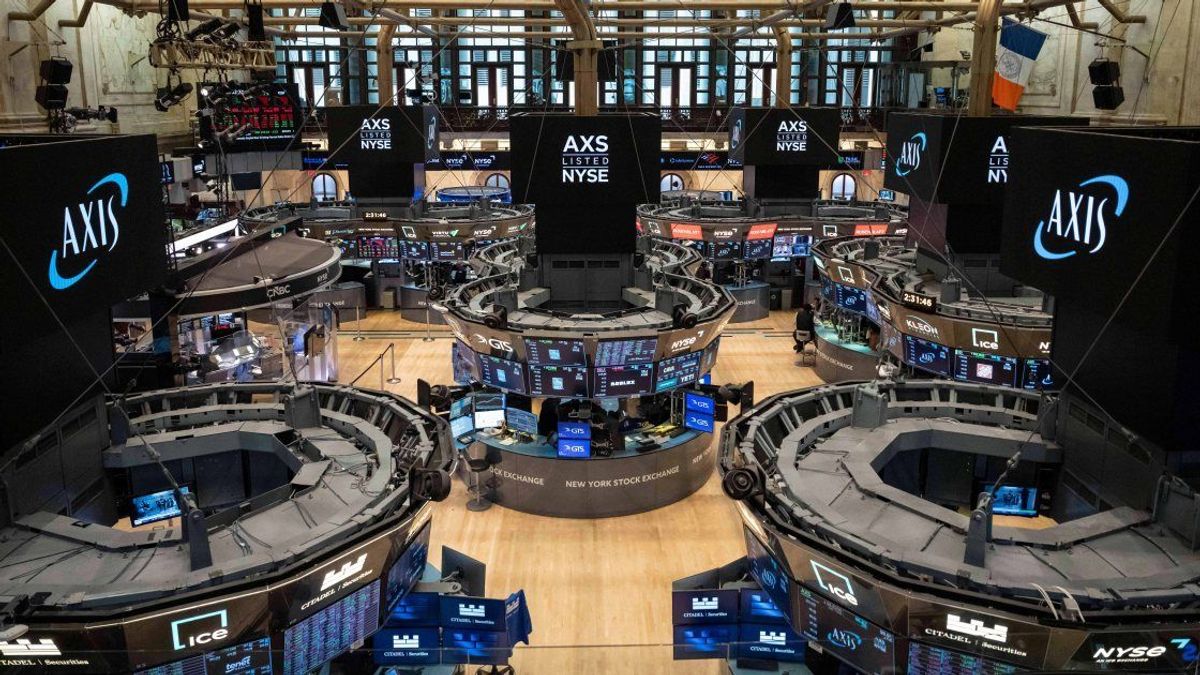
Global equity markets climbed on October 28, 2026 as investors doubled down on artificial intelligence. In the United States, the Nasdaq Composite jumped 1.18%, while the S&P 500 and Dow Jones nudged higher. Tech titans such as Tesla, Amazon, Apple, Alphabet, and Nvidia all posted gains, with Nvidia edging up after a $3 billion stake in Meta’s equity round. Across the Asia‑Pacific, South Korea’s KOSPI surged 5.84% following SK Hynix’s record‑breaking earnings, and Japan, Taiwan, and Australia posted modest advances. The rally unfolded amid a broader AI investment forecast of $2.7 trillion for 2026, while oil prices rose on the back of the US‑Israel‑Iran conflict.
- Capital allocation and corporate survival – Venture capital and public market funds have redirected billions into AI compute, cloud infrastructure, and chip design, betting that the next wave of productivity will come from large‑scale models. Companies like Microsoft and Alphabet are racing to embed AI across software suites, turning AI into a revenue engine that justifies soaring R&D budgets.
- Geopolitical competition – The AI race mirrors the Cold War tech rivalry, with the United States, China, and the European Union each issuing national AI strategies, subsidies, and export controls. The influx of private capital amplifies state ambitions, as governments count on private sector breakthroughs to secure strategic advantage.
- Supply‑chain leverage – Memory‑chip makers such as SK Hynix, Samsung, and Micron have become indispensable nodes in the AI hardware chain. Their profit spikes translate into higher bargaining power over raw‑material exporters and labor forces in East Asia.
- Energy market entanglement – AI data centers are energy‑intensive, linking the tech rally to higher oil demand. The ongoing Middle‑East conflict has pushed Brent crude to $115 a barrel, indirectly inflating operating costs for AI‑heavy firms and tying their fortunes to geopolitical volatility.
- Financial market dynamics – Index funds and algorithmic traders amplify price movements. The “Magnificent Seven” effect creates a feedback loop: rising share prices attract more inflows, which further lift valuations, regardless of underlying earnings.
Workers in semiconductor fabs across South Korea, Taiwan, and the United States face longer shifts, heightened safety risks, and limited bargaining power as firms chase ever‑faster production cycles. The surge in memory‑chip profits masks a rise in occupational injuries and overtime‑driven fatigue.
AI‑driven platforms are automating tasks previously done by freelancers and gig workers. While investors celebrate efficiency gains, many independent contractors see reduced hours and lower pay as algorithms reallocate work to cheaper, automated alternatives.
Retirees whose savings sit in index funds are now exposed to heightened volatility. A sudden correction in AI‑laden equities could erode retirement portfolios, disproportionately affecting older citizens who lack alternative income sources.
Rare‑earth mining in the Democratic Republic of Congo and Australia fuels AI hardware production. Communities near mining sites endure environmental degradation, health hazards, and limited economic diversification, while the profits flow to multinational corporations and distant investors.
Corporate earnings calls and market analysts repeatedly stress “long‑term growth” while sidelining warnings of a speculative bubble reminiscent of the 2000 dot‑com crash. The narrative of inevitable AI profit growth downplays the possibility of a sharp market correction.
Policy briefs from the U.S. Treasury and European Commission highlight AI as a catalyst for job creation, yet they omit discussion of workforce displacement and the need for robust retraining programs. The rhetoric serves to sustain public support for large fiscal incentives.
Data‑center expansion and chip fabrication consume vast electricity and water. Industry reports often gloss over the carbon footprint and water scarcity implications, allowing firms to present AI investment as a clean‑tech story.
Supply‑chain audits rarely capture the lived realities of factory floor workers or miners. By focusing on compliance checklists rather than wage adequacy and health standards, corporations sidestep accountability for the human toll of rapid AI scaling.
- Upcoming earnings – Microsoft, Alphabet, Amazon, and Apple will report in the next week. Their guidance will signal whether AI spending translates into sustainable profit or merely inflates valuations.
- Regulatory signals – The U.S. Securities and Exchange Commission and the European Securities and Markets Authority are drafting AI‑specific disclosure rules. Watch for requirements that could force firms to reveal AI‑related cost structures and risk assessments.
- Energy price volatility – Any escalation in the Middle‑East conflict could push oil higher, squeezing data‑center operating margins and testing the resilience of AI‑heavy balance sheets.
- Labor activism – Unions in South Korea and Taiwan have begun organizing around overtime caps and safety standards. Their success could reshape cost dynamics for chip manufacturers.
- Supply‑chain diversification – Nations like India are courting AI hardware firms with tax breaks, aiming to shift some production away from East‑Asian hubs. Shifts in manufacturing geography could alter geopolitical leverage.
By tracing the flow of capital, policy, and labor, readers can see beyond headline‑grabbing stock gains to the power structures that shape everyday lives. The AI rally is not just a market story; it is a contest over who controls the next wave of productivity, who profits, and who bears the hidden costs.
Investors see AI as the next engine of productivity, pouring capital into firms that build models, chips, and cloud services. The expectation of outsized future earnings lifts valuations across tech and related sectors.
A slowdown in corporate earnings, tighter regulation, or a spike in energy costs could expose over‑optimistic valuations, triggering a sell‑off similar to the dot‑com bust.
Higher demand for chips pushes factories to increase output, often extending work hours and intensifying safety risks for laborers, while wages and bargaining power remain limited.
Editor's Note: Analysis based on publicly reported market data and industry trends up to October 2026.
Source referenced: ALJAZEERA
This brief was synthesized by our Editorial Engine and reviewed by The Ground Narrative team.