TRENDING

Tuesday, 6 October 2026
----------------------
25 Rabi' Al-Thani 1448 AH
A recent The Economist poll shows a clear swing toward China across Latin America, while approval of the United States falls. The shift reflects deeper economic ties, diplomatic outreach, and the fallout from a confrontational U.S. stance.
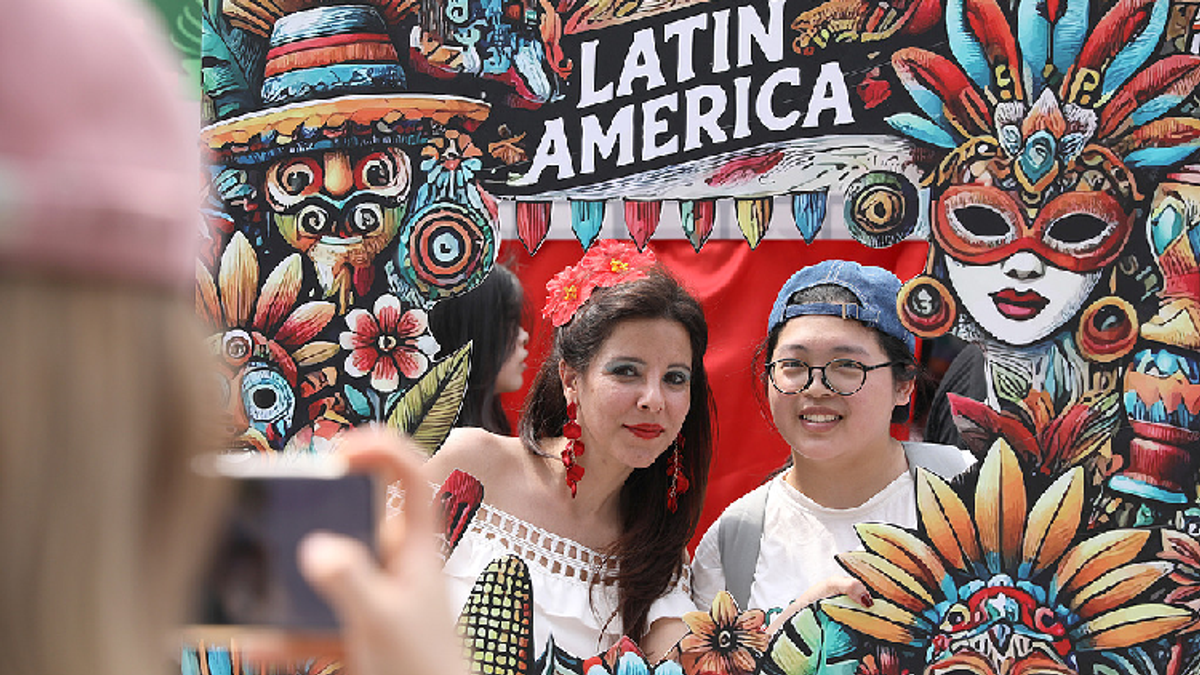
A September 30 poll released by The Economist finds that favorable opinions of China have risen in 15 of the 17 Latin American nations surveyed, while views of the United States have slipped in the same 15 countries. The median share of respondents rating China positively sits at 46 %, compared with 36 % for the United States. The report notes that former President Donald Trump’s hard‑line rhetoric toward the region contributed to the decline in U.S. favorability, echoing similar findings from a July Pew Research Center study.
China has spent the last decade weaving a dense web of trade, investment, and cultural exchange across Latin America. The Belt and Road Initiative (BRI) funded ports in Brazil, highways in Mexico, and mining projects in Peru, creating a perception that Beijing is a partner willing to fund infrastructure without the political conditions traditionally attached to Western aid. At the same time, China’s state‑owned enterprises have flooded local markets with affordable consumer goods, reshaping supply chains and lowering prices for millions of shoppers.
In Washington, the post‑Trump administration has signaled a desire to re‑engage, but congressional gridlock and competing priorities—particularly the focus on the Indo‑Pacific—have limited concrete policy moves. The United States still commands a sizable military presence in the Caribbean and maintains historic trade ties, yet its diplomatic messaging often emphasizes democracy promotion and human‑rights concerns, which can appear intrusive to governments seeking rapid development.
The political calculus for Latin leaders is equally pragmatic. Aligning with China offers a hedge against U.S. pressure, especially for countries like Venezuela and Bolivia that face sanctions. For export‑driven economies such as Chile and Argentina, Chinese demand for commodities—copper, soy, lithium—provides a reliable revenue stream that can offset volatile global markets. The survey’s rise in favorability therefore reflects not just sentiment but a strategic balancing act between two global powers.
While Chinese loans fund visible projects, they also create long‑term fiscal obligations. Nations such as Ecuador and Panama have taken on sizable sovereign debt denominated in yuan, raising concerns about repayment capacity. Critics argue that debt‑service payments divert resources from health, education, and social safety nets, leaving vulnerable populations to bear the brunt of austerity measures.
The influx of cheap Chinese manufactured goods has pressured local factories, leading to layoffs in sectors like textiles and footwear in Mexico and Colombia. Conversely, Chinese‑backed mining and energy ventures have attracted migrant labor from rural areas, often under precarious contract conditions. Workers report limited bargaining power, inadequate safety standards, and a lack of union representation.
Large‑scale infrastructure projects—hydroelectric dams in the Amazon basin, coastal ports in Uruguay, and road expansions in the Andes—displace indigenous communities and threaten fragile ecosystems. Environmental NGOs warn that the speed of Chinese‑led development outpaces local regulatory oversight, exacerbating deforestation, water contamination, and loss of cultural heritage.
Official statements from both China and the United States frame the narrative as one of partnership versus interference. China highlights its “win‑win” cooperation, emphasizing infrastructure and technology transfer, while downplaying the debt burden and the limited local content requirements in many contracts. The U.S. government, meanwhile, stresses democratic values and strategic competition, often omitting the fact that many Latin elites profit directly from Chinese contracts, receiving commissions, land deals, or political capital.
Corporate lobbying further muddies the picture. Major U.S. agribusinesses and energy firms continue to lobby Congress for favorable trade terms, yet their public messaging rarely acknowledges the growing competition from Chinese firms that are now supplying the same markets at lower prices. In Latin capitals, Chinese state‑run media outlets and cultural centers receive tax‑exempt status, a privilege not equally extended to U.S. cultural institutions, subtly skewing public exposure.
Finally, the survey itself may mask regional nuances. While the median favorability for China is 46 %, pockets of resistance remain strong in countries like Chile, where civil society groups protest Chinese mining projects for environmental reasons. The headline figure can obscure these internal debates, leading policymakers abroad to assume a monolithic shift that does not exist on the ground.
- Election cycles: Upcoming presidential elections in Mexico, Brazil, and Argentina will test whether candidates can leverage Chinese goodwill or must pivot back toward the United States to secure financing.
- Debt renegotiations: Watch for sovereign debt restructuring talks involving Chinese creditors, especially in Ecuador and Panama, which could set precedents for future BRI projects.
- Technology standards: The rollout of Chinese 5G equipment and digital payment platforms across the region may create new dependencies on Beijing’s tech ecosystem, prompting a regulatory response from Washington.
- Civil society pushback: Environmental and labor NGOs are beginning coordinated campaigns against specific Chinese projects; their success could influence public opinion and force governments to adopt stricter oversight.
- U.S. diplomatic recalibration: Any substantive shift in U.S. policy—such as a new trade agreement or a high‑level summit focused on Latin America—will be a litmus test for whether the United States can regain lost goodwill.
Staying attuned to these developments will reveal whether the current tilt toward China is a temporary response to U.S. missteps or a longer‑term realignment of power in the Western Hemisphere.
The Economist’s September poll shows that 46 % of respondents across 17 Latin American countries view China favorably, while only 36 % hold a positive view of the United States. Favorability for China rose in 15 nations, whereas U.S. approval fell in the same 15.
Growing Chinese investment in infrastructure, reliable commodity demand, and the perception of fewer political conditions have made Beijing an attractive partner. At the same time, U.S. diplomatic rhetoric—especially under former President Trump—has been seen as confrontational, prompting many governments to seek alternatives.
Editor's Note: Analysis based on publicly available survey data and established patterns of Chinese investment in Latin America.
Source referenced: CGTN
This brief was synthesized by our Editorial Engine and reviewed by The Ground Narrative team.